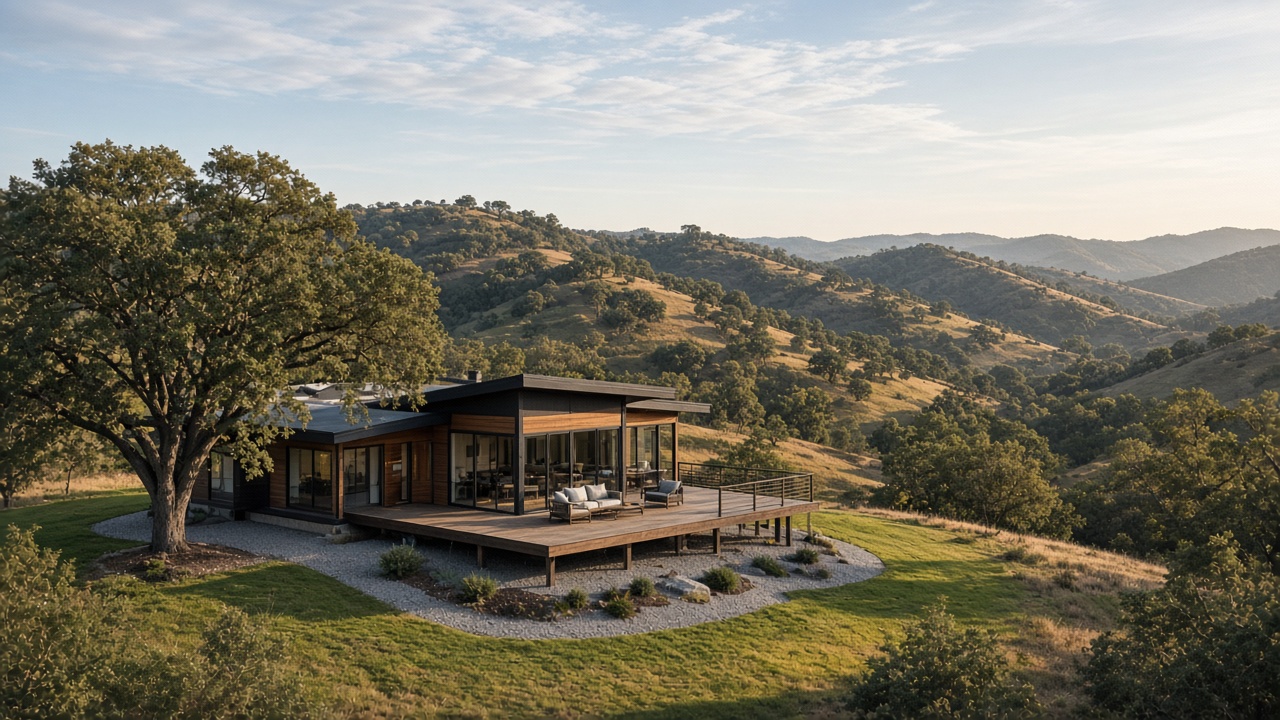
Hillside views are some of the most sought-after features in Morgan Hill real estate. But before you list, there’s a critical conversation most agents won’t have with you.
Morgan Hill Hillside Homes: A Market That Rewards the Prepared
If you own a home on the hillsides east or west of downtown Morgan Hill, you’re sitting on something many buyers are actively looking for. If your home has panoramic valley views, a private setting on an oak-studded lot, or the elevation and quiet that buyers escape Silicon Valley to find — you hold the cards.
What’s driving this? A convergence of factors: continued remote-work flexibility extending buyers’ geographic radius from San Jose and the Peninsula, extremely limited new construction in the foothills, and the enduring lifestyle appeal of South County — wineries, open trails, Uvas Reservoir, and some of the best weather in the Bay Area.
The Premium Properties: What Makes Hillside Homes Different
Not all Morgan Hill homes are created equal. The hillside properties — those tucked into the Diablo Range foothills to the east, or along the Santa Cruz Mountains western slopes — offer things flat-land homes can’t. On the east side, the established hillside neighborhoods of Jackson Oaks and Holiday Lake Estates, both reached by East Dunne Avenue, are good examples. Here’s why buyers value these homes, and what sellers need to understand to capture maximum value.
Scarcity Drives Premium
There simply aren’t many hillside lots left in Morgan Hill. Zoning constraints, wildland-urban interface regulations, and the simple geography of the Santa Clara Valley floor mean that elevated, view-oriented properties are in finite supply. Buyers who want land, privacy, and a genuine sense of arrival at their home know this — and bid accordingly.
The View Premium
Properties with documented valley views — especially those oriented to capture sunrise over the Diablo Range or the wine country hills to the south — are exactly what many hillside buyers are searching for. The right positioning and photography is how that value gets unlocked.
Lifestyle Demand
Many of the buyers competing for hillside homes are looking for space, nature proximity, and outdoor living. A home with a wraparound deck, mature oak trees, and a half-acre of privacy is not a luxury to these buyers. It is a priority.
How to Maximize Your Hillside Premium
- Twilight photography and drone footage — Hillside homes look dramatically different from the air and at golden hour. Standard daytime photography leaves part of your story untold.
- Stage outdoor living areas intentionally — Decks, patios, and fire pits should be staged as additional rooms, not afterthoughts. Buyers pay for the lifestyle, not just the square footage.
- Clarify water source and infrastructure — Some hillside homes in the area operate on private wells or have longer utility runs. Disclose early and explain the advantage of self-sufficiency where applicable.
- Defensible space documentation — If you’ve invested in brush clearance and fire-resistant landscaping, document it thoroughly. This directly addresses buyer concerns and distinguishes you from uninvested sellers.
- Pre-list inspection and disclosure package — Hillside homes often have unique structural considerations (retaining walls, drainage, slope). A thorough pre-list inspection removes buyer uncertainty and supports pricing confidence.
The Truth About Fire Insurance — What Sellers (and Buyers) Need to Know in 2026
Here is where many listing agents change the subject. We won’t. If your property sits in a designated High or Very High Fire Hazard Severity Zone — and many Morgan Hill hillside homes do — fire insurance has become one of the most consequential variables in your transaction. Buyers are asking about it before they ask about the kitchen. Lenders require it. And the landscape in California has shifted fundamentally.
Seller’s Disclosure Obligation
California law requires sellers to disclose if a property is in a High or Very High Fire Hazard Severity Zone. This includes the Natural Hazard Disclosure report. Failure to disclose can expose sellers to significant liability even after close of escrow.
What Has Changed: The Insurance Market in 2026
The devastating Los Angeles wildfires of January 2025 added new pressure to a California home insurance market where several major carriers had already pulled back on writing new policies. The California FAIR Plan — the state’s insurance backstop program — has faced historic pressure, seeking rate increases and navigating a $1 billion emergency assessment to cover Palisades and Eaton Fire claims.
Under the state’s Sustainable Insurance Strategy, insurers that use wildfire catastrophe models in their rates must commit to writing more policies in wildfire-distressed areas. That may expand options over time — but buyers still need to work harder to find coverage, and sellers who proactively address insurance will have a meaningful competitive advantage.
The Three Insurance Paths for Hillside Buyers
- Standard market carrier (a traditional homeowners policy) — Full coverage: fire, liability, personal property, and loss of use. Availability can be limited in higher-risk areas.
- California FAIR Plan (the state-backed last resort) — Limited, fire-focused coverage that does NOT include liability, theft, or water damage. It requires a separate “wrap” policy.
- Surplus lines and specialty carriers (non-admitted insurers) — Broader coverage, but terms vary significantly, there is less regulatory protection, and it is available but expensive.
Critical Buyer Awareness
The California FAIR Plan does not provide a full homeowners insurance policy. Its dwelling policy covers fire and a short list of other named perils. Buyers relying solely on the FAIR Plan will have no liability coverage, no theft coverage, and no water damage protection. A “wrap” policy from a secondary carrier, known as a Difference in Conditions (DIC) policy, is typically required alongside it — adding complexity and cost.
What Smart Sellers Are Doing Now
The sellers winning in this market aren’t hiding the insurance situation — they’re getting ahead of it. Here’s the playbook that experienced listing agents are recommending for hillside properties in Morgan Hill:
- Obtain a current insurance quote before listing — Knowing what coverage costs and is available for your specific parcel eliminates the most common buyer anxiety. Share this proactively in your disclosure package.
- Complete and document your defensible space — CAL FIRE’s defensible space rules cover the area within 100 feet of structures. Compliance not only reduces your fire risk — it can improve your insurance options and buyer confidence.
- Consider Class A fire-rated roofing upgrades — Tile and metal roofs are generally more insurable than wood shake. If your roof is due for replacement, this upgrade can widen your choice of carriers.
- Connect buyers with a broker who specializes in high-risk zones — Recommend an insurance broker familiar with the FAIR Plan and surplus lines market. Buyers who can’t get a firm insurance commitment may be able to cancel during their contingency period, depending on the terms of their purchase contract.
- Highlight ember-resistant features — Enclosed eaves, ember-resistant vents, non-combustible cladding, and tempered glass windows are all features that can help buyers qualify for standard market coverage rather than the FAIR Plan. If you have them, document them.
Seller’s Advantage
Sellers who complete a home hardening assessment, maintain defensible space documentation, and can provide buyers with an active insurance quote at listing make it easier for buyers to move forward with fewer contingency headaches. Being the “easy” transaction matters to buyers navigating complexity elsewhere in their lives.
Your 2026 Listing Playbook: Timing and Positioning
If you’re considering listing this year, the window from March through June typically captures the highest buyer activity and most competitive offer environments.
Timing Your Listing for Maximum Competition
Homes listed on a Thursday or Friday get a full weekend of showings, allowing sellers to collect competing offers by the following Monday. For hillside homes where outdoor presentation is critical, listing after a week of good weather — when your landscaping looks its best and the valley views are clear — can meaningfully impact first impressions and offer quality.
Pricing Strategy: The Danger of Overreaching
Disciplined pricing beats wishful thinking. Sellers who list at or slightly below market value to generate competitive bidding often do better than those who anchor high and wait. A home that sits while competing homes go under contract signals problems to buyers — even if none exist. Price with precision, not hope.
What Buyers Are Asking About Right Now
- Fire insurance availability and current quotes for the specific parcel
- CAL FIRE defensible space compliance and when it was last inspected
- Well or public water, and well flow rates where applicable
- Roof age and material (critical for insurance qualification)
- Septic system condition and last pump date
- Internet connectivity — remote workers won’t compromise on this
- Hillside access and road conditions, especially in wet weather
Sellers who prepare clear, documented answers to each of these questions before their first showing create an environment of confidence. Buyers who feel informed are buyers who bid confidently — and that confidence translates directly to offer price and terms.
In 2026, the hillside sellers who win aren’t just the ones with the best views. They’re the ones who’ve done the homework — on insurance, on disclosure, on defensible space — and made it easy for a buyer to say yes.
Ready to Find Out What Your Hillside Home Is Worth?
Get a complimentary market analysis specific to your property — including an insurance landscape overview for your parcel and a custom pricing strategy. Request your free home valuation. No obligation · Responds within 24 hours · Morgan Hill specialist
Avil Soleiman | Broker, Avil Soleiman Brokerage | DRE #01968159
This article is intended for general informational purposes. Real estate and insurance decisions should be made in consultation with licensed professionals. Insurance availability and rates are subject to change.